
Molasses Market Size Set to Reach $11.80 Billion by 2031 Driven by Clean-Label Sweeteners and Bioethanol Production – Mordor Intelligence
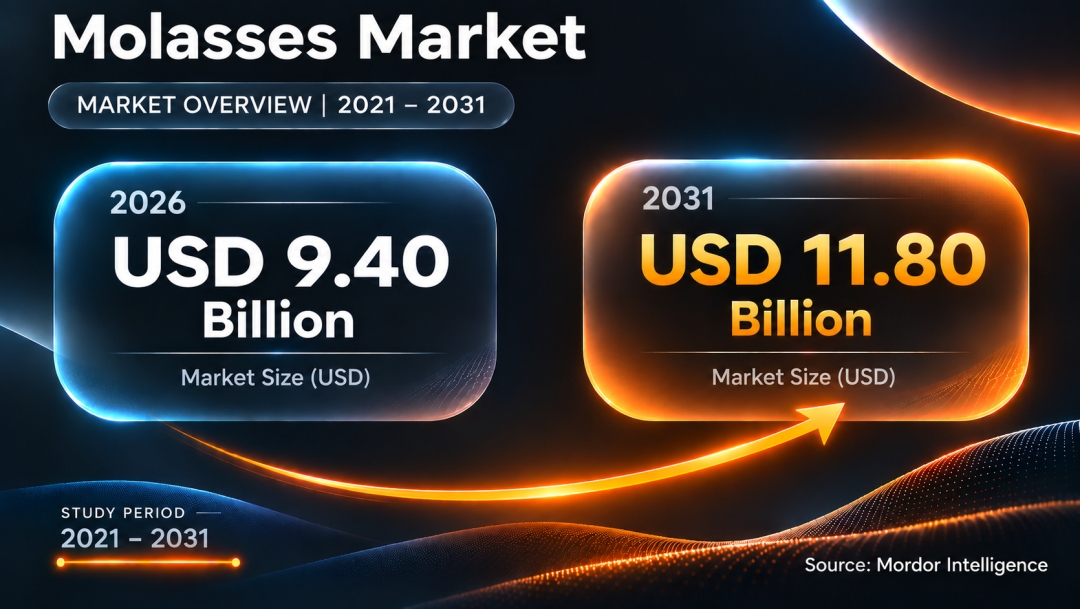
Hyderabad, November 11, 2026: According to Mordor Intelligence, the molasses market size was valued at $9.40 billion in 2026 and is projected to reach $11.80 billion by 2031, registering a 4.66% CAGR during the forecast period (2026-2031). The market expands as commercial livestock producers, bioethanol distillers, and industrial food processors source viscous sucrose co-products for low-cost energy supplementation, clean-label sweetening, and fermentation feedstock. Supported by its Generally Recognized as Safe (GRAS) status, molasses serves as an indispensable carbohydrate source across ruminant feeding protocols, commercial bakery goods, and renewable transportation fuels. Expanding commercial feed compound mills, ongoing biofuel blending mandates, and shifting consumer preferences for unrefined food sweeteners support steady procurement volumes across global agricultural and manufacturing hubs.
The molasses market growth is also shaped by sugarcane harvest yields, regional sugar beet processing cycles, and changing government biofuel directives. Commodity traders and industrial processing mills are investing in specialized heated bulk storage tanks, automated micro-pulverizing drying lines, and intermodal tank container logistics. These logistical improvements help agricultural processors manage feedstock availability and seasonal crushing fluctuations while maintaining target Brix levels, fermentable sugar content, and microbial stability. Together, these operational factors strengthen the integrated molasses market forecast across primary agricultural trade corridors and emerging consumer markets.
Molasses Market Trends
Animal Feed Compounding and Palatability Enhancement Drive Bulk Volume Consumption
One of the leading molasses market trends is the high utilization of cane and beet syrups as nutritional binders in commercial animal feed formulations. In intensive dairy and poultry operations, liquid molasses enhances feed palatability, stimulates dry matter intake, and suppresses respiratory dust in mash and pellet diets. Beyond supplying readily available sucrose for rumen microbes, molasses delivers essential trace minerals, including potassium, magnesium, and calcium. Commercial livestock operators and premix blenders increasingly formulate liquid molasses into total mixed rations, supporting the molasses industry.
Enteric Methane Mitigation in Ruminants Boosts Blackstrap Molasses Adoption
Livestock environmental sustainability initiatives represent an expanding development area within the molasses market share. Dairy and beef producers face increasing regulatory pressure to lower greenhouse gas emissions from cattle. Feeding protocols that integrate blackstrap molasses with targeted mineral buffers and non-protein nitrogen have demonstrated notable reductions in enteric methane production. The concentrated mineral matrix and sulfur compounds in third-boiling blackstrap molasses optimize rumen fermentation efficiency, shifting hydrogen allocation away from methanogenic archaea toward propionate synthesis. This functional attribute aligns with broader benchmarks recognized across the integrated food ingredients industry for sustainable agricultural nutrition.
European Renewable Energy Mandates Accelerate Sugar Beet Molasses Utilization
Biofuel policy enforcement continues to guide the molasses market growth. In Europe, the revised Renewable Energy Directive (RED II and RED III) establishes strict targets for advanced and waste-based biofuels. Sugar beet processors across France, Germany, and Poland increasingly divert beet molasses directly into integrated ethanol fermentation distilleries to fulfill regional transport decarbonization quotas. This diversion of high-sugar co-products toward clean fuel production tightens commercial availability for traditional industrial buyers, supporting baseline price stability across European distribution terminals.
Clean-Label Food and Beverage Formulations Favor Natural Brown Coloring and Sweetness
Product formulation shifts guide consumer goods procurement patterns. Food and beverage manufacturers are replacing synthetic caramel colorings and refined corn syrups with unrefined cane and blackstrap molasses in artisan breads, barbecue glazes, functional beverages, and gingerbread confectionery. In addition to delivering distinct bittersweet flavor notes, dark molasses acts as a natural humectant that maintains crumb moisture in shelf-stable baked goods. Food processors emphasize the natural origin and clean-label appeal of molasses on packaging to satisfy consumer demand for minimally processed ingredients.
Asia-Pacific Retains Regional Dominance While South America Leads Global Export Shipments
Regional supply and consumption dynamics continue to guide the molasses market forecast. The Asia-Pacific region holds the largest regional market share and registers steady consumption growth, propelled by extensive sugarcane milling in India and Thailand, expanding commercial compound feed industries, and national ethanol blending targets. Meanwhile, South America, anchored by Brazil’s cane processing infrastructure, commands international maritime export trade. Brazilian sugar-energy groups efficiently allocate liquid cane molasses between domestic anhydrous bioethanol production and ocean-going bulk parcel tankers to maximize export returns.
Check out more details and stay updated with the latest industry trends, including the Japanese version for localized insights: https://www.mordorintelligence.com/ja/industry-reports/molasses-market?utm_source=abnewswire
Molasses Market Segmentation
By Source
- Sugarcane
- Sugar Beet
- Others (Citrus, Sorghum, Pomegranate)
By Grade
- First/Light Molasses
- Second/Dark Molasses
- Blackstrap Molasses
By Form
- Liquid
- Powder/Granules
By Application
- Animal Feed and Pet Food
- Biofuel/Ethanol
- Food and Beverage (Bakery, Confectionery, Sauces, and Alcoholic Beverages)
- Others (Industrial Fermentation, Pharmaceuticals, Soil Conditioning)
By Geography
- North America
- Europe
- Asia-Pacific
- South America
- Middle East and Africa
Competitive Landscape of the Molasses Industry
The molasses industry exhibits a moderately consolidated competitive structure, with multinational agribusiness corporations, international sugar milling groups, and specialized commodity logistics firms competing across storage tank capacity, ocean chartering networks, and multi-origin procurement contracts. Market participants strengthen their operational presence by acquiring regional port terminals, upgrading liquid handling pumping stations, and establishing long-term off-take agreements with independent sugar mills.
Brix concentration, total fermentable sugar content, and free-flowing viscosity control serve as primary areas of operational differentiation. Suppliers invest in specialized blending infrastructure to deliver customized brix grades and low-viscosity formulations that pump efficiently through automated feed mill injection systems in cold climates. Commodity handlers also collaborate directly with commercial bioethanol plants and commercial bakeries to provide vendor-managed liquid bulk storage. These initiatives help major suppliers protect their molasses market share while navigating harvest-cycle price volatility.
Global logistics management and multi-origin sourcing remain standard business practices. Leading agricultural traders maintain dedicated deep-water liquid bulk terminals near primary sugar export centers in South America and Southeast Asia to minimize ocean transit delays. As commercial demand for renewable biofuels, sustainable animal feed supplements, and natural food ingredients continues worldwide, the molasses market forecast remains supported by ongoing capital investments in automated drying facilities, port infrastructure, and international trade partnerships.
Key Players
Major companies operating in the molasses market include:
- Wilmar International Limited
- Cargill, Incorporated
- The Archer-Daniels-Midland Company
- Louis Dreyfus Company
- Hartree Partners (ED&F Man Holdings)
Conclusion
The molasses market forecast points toward steady expansion as livestock producers, bioethanol refiners, and food manufacturers continue utilizing sugar refining co-products for cost-effective animal nutrition, clean energy, and natural food formulation. Commodity processors and agribusiness operators respond by expanding bulk liquid terminal networks, refining spray-dried powder processing, and engineering specialized liquid feed blends that enhance rumen fermentation while reducing livestock enteric methane emissions. These operational developments support sustained procurement across high-capacity feed mills, industrial distilleries, and commercial food bakeries worldwide.
Managing raw crop availability and securing specialized bulk liquid freight assets remain essential operational priorities for distribution businesses. Meanwhile, the steady adoption of unrefined blackstrap molasses in clean-label food products enables commercial food brands to replace artificial colorings and refined sweeteners while meeting precise culinary flavor standards. These practical processing adjustments continue to guide modern molasses market trends.
Regional conditions offer balanced commercial opportunities. Asia-Pacific provides an expanding, high-volume consumption base supported by intensive livestock farming and national biofuel programs, while South America anchors international trade flows through extensive sugarcane crushing complexes. These complementary regional positions create clear commercial routes for industrial molasses distributors worldwide.
Overall, the molasses market size will continue to benefit from shifting animal welfare practices, growing demand for renewable biofuels, wider availability across bulk maritime shipping networks, and ongoing improvements in feed formulation science. These combined market factors support sustained molasses market growth while reinforcing the commercial position of the global molasses industry.
Industry Trending Reports
Sugar Toppings Market Size: The global sugar toppings market is valued at $10.26 billion in 2026 and is projected to expand to $13.84 billion by 2031, registering a 6.12% CAGR. Market momentum is driven by quick-service restaurant footprint expansion, home-baking trends, and demand for photogenic syrups and dessert finishes. To counter commodity price swings across sugar and cocoa alongside European restrictions on synthetic color additives, manufacturers are reformulating portfolios with plant-based stabilizers, clean-label coloring agents, and localized botanical flavor infusions.
Sugar Alcohols Market Share: The global sugar alcohols market was valued at $4.10 billion in 2025 and is estimated to grow from $4.36 billion in 2026 to reach $5.95 billion by 2031, registering a CAGR of 6.42%. Market growth is propelled by the widespread adoption of polyols as non-cariogenic sweeteners, low-calorie bulking agents, and functional humectants across food, oral care, and pharmaceutical formulations. In response to Western trade actions and regulatory pressure for clean supply chains, processors are investing in traceable, fermentation-derived polyols while expanding high-purity, excipient-grade sorbitol and erythritol lines.Read Full Report: Sugar Alcohol Market Growth & Forecast
Global White Sugar Market Trends: The global white sugar market is valued at $72.62 billion in 2026 and is forecast to climb to $97.73 billion by 2031, growing at a 6.12% CAGR. Stable baseline volume is anchored by industrial food and beverage processing, alongside rising demand for bioethanol and bio-based chemical feedstocks. Cane-sugar refiners in Brazil, India, and Thailand maintain operational flexibility between ethanol and crystal sugar, while processors increasingly adopt automated liquid sugar delivery systems to enhance dosing efficiency in modern food manufacturing plants.
About Mordor Intelligence:
Mordor Intelligence is a global market intelligence firm, founded in 2014, helping businesses make informed decisions through data-driven insights, industry expertise, and advanced analytics. With 550+ domain experts and on-ground specialists across 180+ countries, the company delivers comprehensive intelligence across aerospace & defense, agriculture, automation, automotive, chemicals & materials, consumer goods & services, electronics, energy & power, financial services, food & beverages, healthcare, hospitality & tourism, information & communications technology, and logistics.
Its offerings include syndicated industry reports, custom research and advisory, and subscription platforms such as Data Center Intelligence. Mordor Intelligence is ISO 9001:2015 and ISO/IEC 27001:2022 certified, a member of ESOMAR and the Market Research Society of India, and a four-time Great Place to Work® honoree. Learn more at mordorintelligence.com
Media Contact
Company Name: Mordor Intelligence
Contact Person: Jignesh Thakkar
Email: Send Email
Phone: +1 617-765-2493
Address:11th Floor, Rajapushpa Summit, Nanakramguda Rd, Financial District, Gachibowli [email protected]
City: Hyderabad
State: Telangana 500008
Country: India
Website: https://www.mordorintelligence.com/industry-reports/molasses-market?utm_source=abnewswire


